Picture this: you’re folding laundry in your cozy kitchen, the scent of fresh apple pie filling the air, and you start wondering how to secure your family’s future without stepping away from the home you love. As a tradwife who’s spent years sharing homemaking wisdom, I’ve chatted with countless women navigating the world of investing while keeping family at the heart of it all.
Basic investing for traditional families isn’t about chasing Wall Street dreams—it’s about building a stable foundation that supports your estilo de vida tradwife. Whether you’re putting aside small amounts each month or planning for your children’s future, investing empowers you to contribute to your family’s financial security from your kitchen table. In this guide, I’ll break down why starting small with investments can strengthen your household, providing security that aligns with our values of home and hearth.
Why investing matters in a traditional home
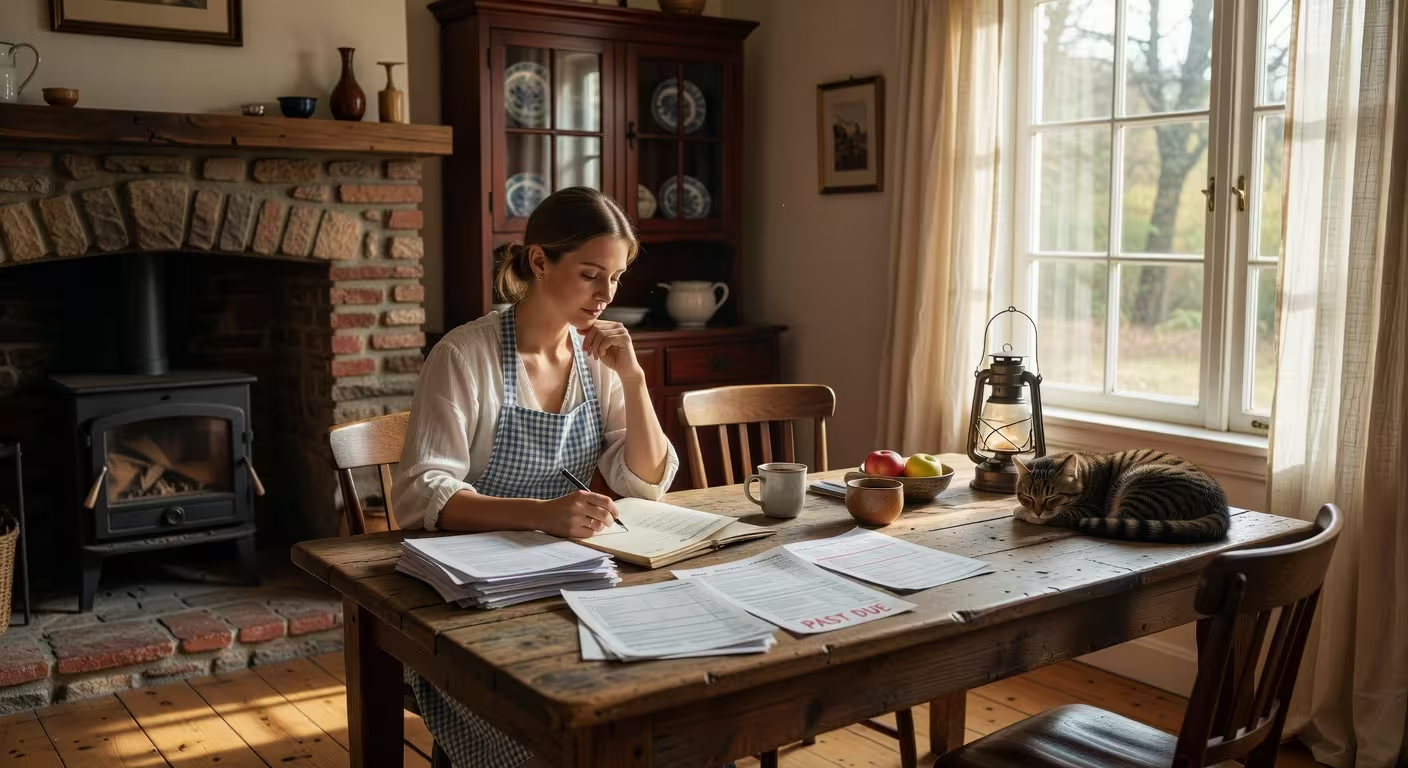
Let’s be real, ladies. Choosing the tradwife path to focus on nurturing our families doesn’t mean we ignore the financial side. I’ve seen women in our comunidade share stories of how a little investing savvy turned their household budgets into something more secure, creating breathing room for the life they truly want.
Think about it. The same frugality that has you stocking up at Costco for winter months or meal planning every Sunday applies to investing. It’s putting money to work so it grows over time, supporting your husband’s efforts without you needing to clock in at an office. You’re contributing to your family’s prosperity in a way that honors your role at home.
Here’s what nobody tells you: starting with basics like a high-yield savings account or bonds can feel overwhelming at first. But once you take that first step, it’s genuinely empowering. I remember chatting with a young wife who worried about unexpected expenses derailing their dreams of a farmhouse-style home. She started with a simple emergency fund invested conservatively, and within two years, it had grown enough to cover a new roof without touching their regular savings. That peace of mind changed everything for her.
That said, this isn’t about getting rich quick or competing with your neighbors. It’s about aligning with our valores—stability, family first, and thoughtful growth. When you approach investing with the same care you bring to planning holiday meals or organizing your pantry, it becomes another extension of your homemaking expertise.

Getting started: simple steps for beginners
I’ll admit, when I first looked into investing, I felt completely lost. But breaking it down into manageable steps made all the difference. If you’re new to this, begin by honestly assessing your family’s finances. What’s coming in each month? What’s going out? Use a simple notebook—nothing fancy, maybe one from a thrift store find—and track everything for thirty days.
Next, set clear goals. Are you saving for a child’s education? Building an emergency fund? Creating a buffer for those unexpected home repairs that always seem to pop up? Short-term goals (under five years) might lean toward high-yield savings accounts or certificates of deposit, while long-term ones could explore stock market index funds or retirement accounts.
Opening your first investment account is easier than you might think. Many traditional families start with a Roth IRA for its tax benefits, especially if you’re not working outside the home. According to IRS guidelines, you can contribute to a spousal Roth IRA even if you don’t have earned income, as long as your husband does. You can set this up online while the kids nap, choosing low-cost providers that don’t require constant monitoring.
The thing is, education matters tremendously. Dive into resources that resonate with our lifestyle—books on household economics that treat investing as part of overall home management. Our lista de leitura includes several titles that approach finances from a family-first perspective.
Between you and me, don’t rush this process. Start small, perhaps with $50 or $100 a month, building that habit like you would a weekly meal plan. Consistency matters far more than the initial amount. I’ve watched women transform their family’s financial picture by investing just $75 monthly for a decade—that’s the power of time and patience working together.

Choosing investments that fit family values
Now, here’s where it gets interesting. Not all investments are created equal, especially when you’re curating a life centered on stability and traditional values. We want options that promote steady growth, not wild speculation that keeps you up at night worrying.
Index funds have become a favorite among homemakers I know. They’re like a well-seasoned cast iron skillet—reliable, low-maintenance, and they appreciate over time. These funds track broad market indexes, giving you instant diversification without the stress of picking individual stocks. The SEC recommends index funds for beginning investors because of their simplicity and typically lower fees.
Bonds offer that steadiness we crave. Government bonds feel safe, like a warm quilt on a fall evening. Treasury bonds, municipal bonds, or even bond funds can provide regular income and stability, especially as you get closer to needing the money. They won’t make you rich overnight, but they won’t give you heart palpitations either.
For those with a bit more adventure in their portfolio, dividend stocks from companies we know and trust can work beautifully. Think household brands you already buy—companies that have been around for decades and pay regular dividends. One mother of three I know invested in a mix of dividend-paying stocks from companies she genuinely believed in, and those quarterly dividend checks now fund their annual family vacation.
I’ll be honest, there’s ongoing debate between aggressive growth strategies and conservative approaches. What I’ve learned through years of conversations is to avoid anything too volatile. Our homes thrive on predictability—the same principle applies to our investments. A balanced approach combining stocks (for growth) and bonds (for stability) often serves traditional families best.
If you’re evaluating different approaches, consider ethical or faith-based investing options. Some funds focus on family-friendly companies, avoiding businesses that conflict with traditional values. These align beautifully with our movement’s principles, letting your money work in ways that reflect what matters most to you.

Common pitfalls and how to avoid them
The truth? Investing isn’t all smooth sailing, even for those of us who’ve been at it a while. I’ve watched women make emotional decisions during market dips, pulling money out at exactly the wrong time. It’s like panic-buying at the grocery store before a storm—understandable, but usually counterproductive.
One major frustration is fees silently eating into your returns. A fund charging 1.5% annually versus one charging 0.15% might not sound like much, but over decades, that difference can cost you tens of thousands of dollars. Always compare expense ratios and choose low-cost providers when possible. Think of it like buying ingredients—you want quality, but you don’t want to overpay unnecessarily.
Another debate centers on timing the market versus time in the market. From real conversations with experienced investors, consistency wins every time. It’s like your reliable mixer churning out dough week after week—steady effort produces better results than trying to guess the perfect moment. Set up automatic investments and let dollar-cost averaging do its work, buying more shares when prices are low and fewer when they’re high.
Here’s the part many skip: diversification. Don’t put all your eggs in one basket, no matter how promising it looks. Spread investments across different types of assets—stocks, bonds, perhaps real estate funds if you’re drawn to that. Diversification is your protection against any single investment going south.
That said, when challenges arise, lean on your support network. Our Boletim informativo regularly features tips from experienced wives who’ve navigated market ups and downs while maintaining their focus on home. You’re not alone in this journey, and there’s wisdom in learning from others’ experiences.
Building wealth while keeping home first
Imagine this: years down the line, your investments have grown enough to fund your daughter’s wedding, replace your aging car without loans, or give your family options during unexpected life changes. It’s absolutely possible without sacrificing your role as the heart of the home.
The key is integration. Set aside time during quiet afternoons—maybe twenty minutes once a month—to check in on your accounts and rebalance if needed. Many women do this while listening to podcasts or during kids’ naptime. It doesn’t require hours of research or constant monitoring; simple, periodic attention is enough.
For families with a marido de aluguel leading the charge financially, make investing a team effort. Schedule quarterly “money dates” over coffee where you review goals together, celebrate progress, and adjust as needed. This keeps both partners informed and aligned, much like coordinating holiday preparations or planning home improvements.

Different stages of your tradwife journey require different approaches. The experienced homemaker might fully automate contributions and rebalancing, freeing her attention for other priorities. The beginner focuses on learning basics and building initial habits, perhaps starting with just a savings account before moving to investments. Both paths are valid—meet yourself where you are.
What I’ve found most rewarding is how investing amplifies the traditional values we already live by. Patience, discipline, planning ahead, delayed gratification—these are the same qualities that make you excellent at meal planning, budgeting, and running a household. You’re not learning something completely foreign; you’re applying skills you already have to a new area.
One practical tip: consider matching your investment contributions to household milestones. Finished paying off a credit card? Redirect that payment to investments. Got a tax refund? Split it between something fun for the family and your investment account. These small redirects add up significantly over time without feeling like sacrifice.
Ultimately, basic investing empowers us to build the secure, stable homes we dream of. It’s a conscious choice that adds tremendous value to traditional family life, creating options and security while honoring the priorities we hold dear. You’re not just managing money—you’re stewarding your family’s future with the same care you bring to everything else in your home.
Ready to take the next step in building your family’s financial foundation? Join other homemakers in the Comunidade Tradwife Club where we share practical tips, celebrate wins, and support each other through every season of this journey. Your future self—and your family—will thank you for starting today.
Perguntas frequentes
What is the best way for a tradwife to start investing with limited funds?
Begin with small, consistent contributions to a low-cost index fund or Roth IRA, which you can set up easily online. Focus on automating deposits from your household budget, starting with as little as $25-50 monthly, to build wealth without daily effort or overwhelming your family’s finances.
How do I talk to my husband about family investments?
Approach the conversation during a relaxed moment over coffee, framing investing as supporting long-term family goals like education or retirement. Share specific ideas you’ve researched and suggest starting with joint goals, making it collaborative rather than confrontational, which honors traditional partnership roles.
Are there investments that align with traditional values?
Yes, faith-based and ethical funds specifically support family-oriented companies while avoiding businesses that conflict with traditional values. Look for funds labeled as socially responsible, faith-based, or ESG (environmental, social, governance) that screen companies based on specific criteria matching your beliefs.
What should I do if the market drops significantly?
Resist the urge to panic-sell; historical data shows markets recover over time, and selling during drops locks in losses. Continue your regular contributions (you’ll actually buy shares at lower prices), maintain your diversified portfolio, and remember you’re investing for decades, not days.
How can investing fit into a busy homemaking schedule?
Set up automatic contributions and let technology handle the day-to-day, checking in quarterly during quieter seasons like after holiday preparations wind down. This “set and forget” approach keeps your focus on home and family while your investments grow steadily in the background.
Can I contribute to retirement accounts if I don’t work outside the home?
Absolutely! A spousal IRA allows non-working spouses to contribute to their own retirement account using the working spouse’s income, with the same contribution limits as traditional IRAs. This ensures homemakers build their own retirement security while focusing on family.